Buying Your First Home With a Small Down Payment in San Diego
I get one question more than any other from couples who have just gotten married, and it usually comes out a little apologetically: is buying a first home in San Diego even realistic when the down payment is small? The couple in this story asked it in almost those words. The wedding had taken most of what they had saved, and every listing they liked seemed to assume a buyer with more cash on hand than they had. I told them what I will tell you, which is that the answer depends far less on the size of the down payment than on how the rest of the deal is put together.
Two months, one townhome, and a number that had to work
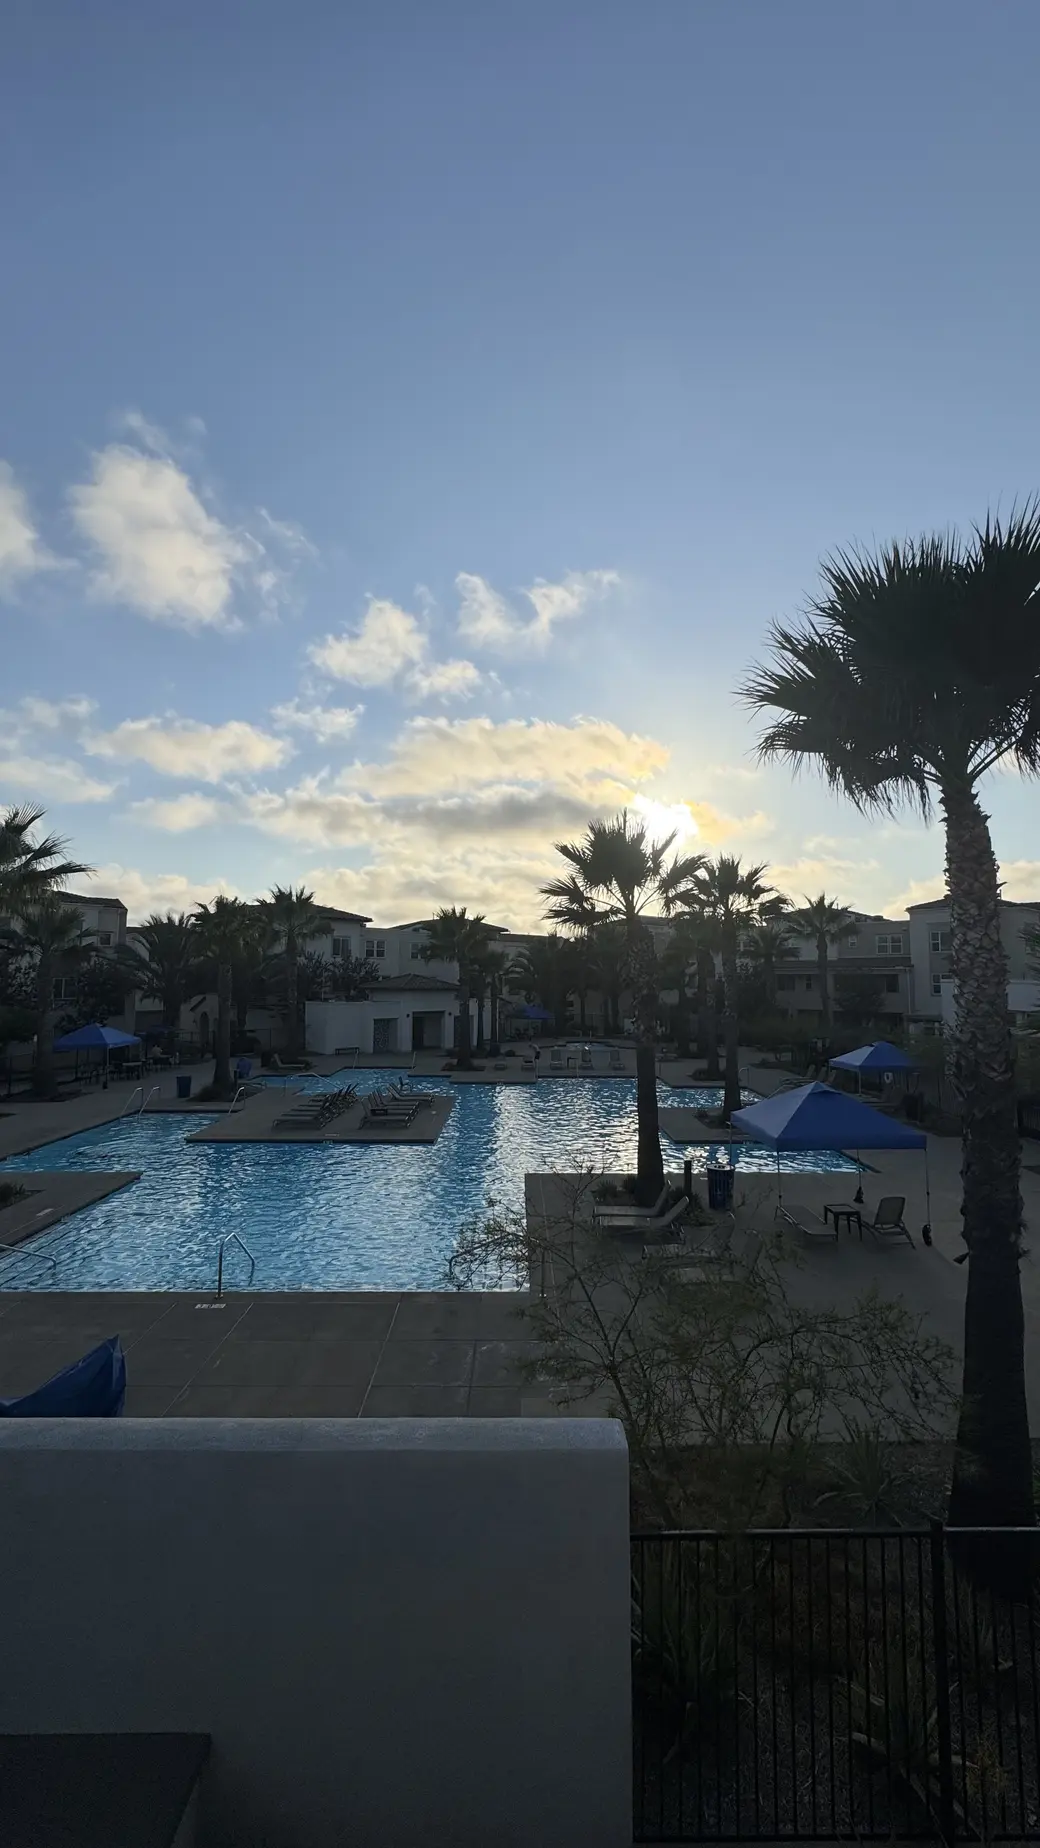
We looked for about two months, and most of the discipline was in what we passed on. There is always more to pass on than to buy when you scroll through homes for sale in San Diego, and that is the point. A lender's pre-approval tells you the top of your budget and says nothing about what you should spend, so we shopped to the monthly payment they could live with, which was a different number than the one they technically qualified for. The townhome that finally fit was a newer build in Chula Vista, and the afternoon we walked through it there were no other offers on the table. By the next morning there were two.
Why the seller took the offer that asked for the most
Ours was the only one of the three that asked the seller for anything. We wrote in a request for $15,000 back at closing, and that money went toward buying down their interest rate, which means paying an upfront cost in exchange for a lower rate for the life of the loan, and toward the closing costs that would otherwise have come straight out of their savings. On paper that should have made us the weakest of the three offers. What the seller actually cared about was whether the deal would close, and every question the listing agent asked, about the loan, about timing, about these particular buyers, got a straight answer the same day from their loan officer or from me. By the end of that day she had stopped asking. Certainty is worth money to a seller, and it cost my clients nothing but preparation.
What the lender brought to it
Their loan officer, someone I have worked with for years, had access to programs for first-time buyers that covered the appraisal fee and several other costs I would normally expect a buyer to pay themselves. Between the seller credit and those programs, the cash they needed to close came down a long way from where we started, and the monthly payment landed where they wanted it. If you want to see what is available in California right now, CalHFA's homebuyer page lists the state's down payment assistance programs, the Consumer Financial Protection Bureau has a plain-English breakdown of who pays which fees at closing, and HUD-approved housing counselors will give you a free second opinion on what you qualify for.
Frequently asked questions
Can a seller pay my closing costs when I buy a home?
Yes, this is called a seller credit or seller concession, and it is negotiated as part of the purchase offer. The amount allowed depends on your loan type and down payment size, so your lender will confirm the maximum before you write the offer.
What does it mean to buy down your interest rate?
Buying down your rate means paying an upfront cost, often covered by a seller credit, in exchange for a lower interest rate on your loan. A lower rate reduces your monthly payment for as long as you hold that rate, which can make a meaningful difference over the life of a 30 year loan.
Is it possible to buy a home with a small down payment in San Diego?
Yes. Between low down payment loan programs, first-time buyer assistance, and negotiated seller credits, buyers with limited savings can still compete, especially outside the highest priced coastal neighborhoods. The right strategy depends on your specific financial picture, which is why I always start there.
What happens when there are multiple offers on a home?
The seller is not required to take the highest price. They can weigh terms, financing strength, and how confident they are that the deal will actually close. A trusted relationship between agents and lenders can influence that decision as much as the number on the offer, and it is the pattern that runs through most of the client stories on my case studies page.
Do first-time buyers have access to special loan programs?
Many do. Programs vary by lender and can include reduced fees, down payment assistance, or credits toward costs like the appraisal. Ask your loan officer specifically what first-time buyer programs they offer, since not every lender provides the same options. If you would like a sense of how I approach that conversation before we talk, my about page covers how I work.
If your down payment feels too small to make this real
A small down payment is not the same as being priced out of San Diego. It means the deal has to be built with more care: the right price rather than the approved price, a seller credit written into the offer, a lender who knows which programs apply to you, and answers that reach the seller the same day they ask. I would rather look at your real numbers with you than have you rule yourself out on a guess.
Shirin Kheshti | Broker Associate, Realtor | MRP Certified | DRE #01848250 | Coldwell Banker West | (858) 750-5753 | Shirin@TheSDHome.com
Categories
Recent Posts


GET MORE INFORMATION